
After two months of falling prices and building inventory, the Denver housing market September 2026 numbers did something they have not done since spring: they mostly held still. The median sold price barely moved, months of supply was essentially flat, and the market settled into the balance it had been drifting toward all summer.
The Big Picture
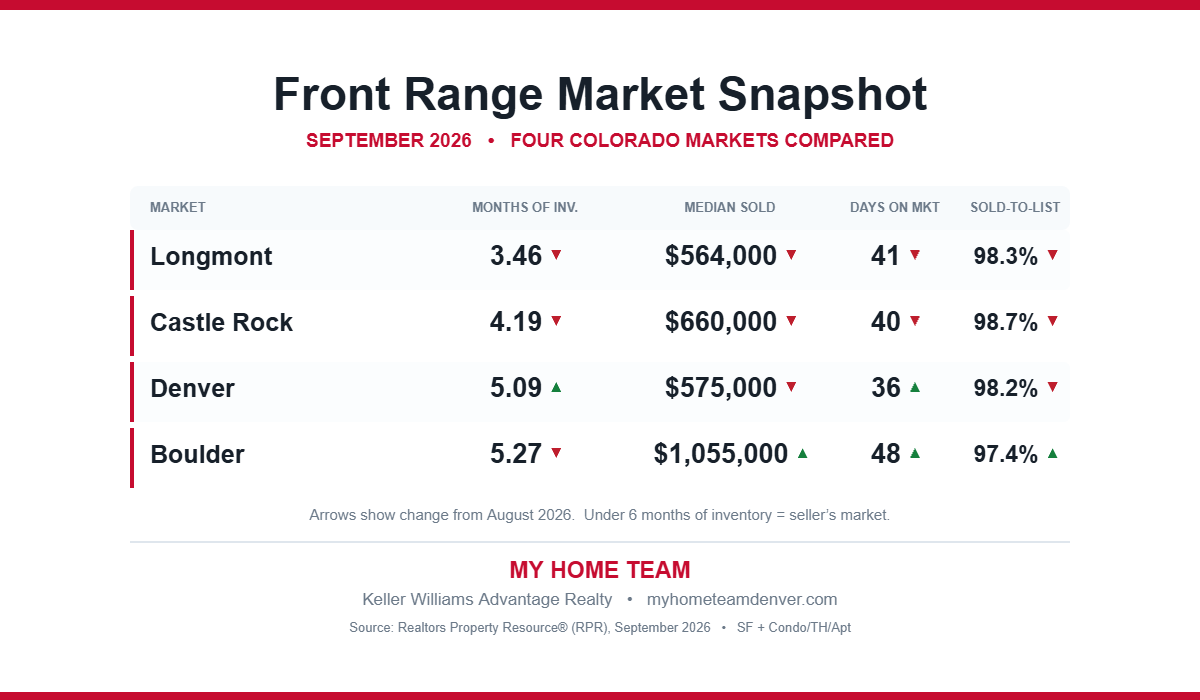
Denver remains in seller’s market territory with 5.09 months of inventory, up just 0.2% from the previous month. Homes sold for 98.2% of list price, down 0.03%, and the median sold price came in at $575,000 — down 0.86%.
Compare that to the prior two months, when the median fell 3.82% in July and 8.73% in August. A 0.86% move is a market finding its floor rather than continuing to slide.
Speed to Sale
The median time a home spent in RPR (Realtors Property Resource) before selling was 36 days, up 9.09% from the prior month. Interestingly, active listings are moving the other way: the median days on market for homes still listed fell 7.5% to 62 days.
That split matters. Sold homes are taking longer, but the standing inventory is turning over faster than it was — a sign that the backlog of stale listings is working through the system.
New Listings Surged
New listings in September totaled 1,338 properties, up 12.4%, at a median list price of $600K — up 7.3% — with total dollar volume of $1.07B, up 20.7%, and a median living area of 1,677 square feet. Median $/sqft on new listings rose 4.5% to $392.
That is a notable jump in both count and price. Sellers who held off during the summer slowdown came to market in September, and they came in asking more. Whether buyers meet those prices is the question October will answer.
Active Inventory
Active listings totaled 3,597 properties, down 1.1%, at a median list price of $525K — up 1.9% — with a median of $375 per square foot and total active dollar volume of $2.61B, up 1.6%. Median living area on active listings was 1,428 square feet.
Pending Activity
New pending listings rose 2% to 606 properties at a median list price of $599.3K, essentially flat, with a median of 33 days in RPR. Pending listings overall climbed 4.2% to 693 properties at a median list price of $599.9K, up 1.7%, sitting a median of 38 days.
Pending listings are homes under contract but not yet closed, which makes them an early read on where sold prices are headed. Denver’s pending median of around $600K sits above the $575K that actually closed in September, suggesting October closings may tick up.
Sold Homes
575 homes sold in September, down 3%, at a median price of $575K and a sold-to-list ratio of 98.15%, unchanged month over month. Total sold volume came to $449.9M, down 1.1%. Median sold price per square foot was $355, down 7.6%.
Property Values
The median estimated property value across Denver came in at $565,870, down 0.5% month over month and down 2.7% over the past 12 months.
Months of Supply: Flat for the Month, Up for the Year
Months supply of inventory sits at 5.09, up 0.2% from last month and up 1.2% over the past 12 months. After climbing through the summer, supply has effectively stopped rising.
What Months of Supply Really Measures
Months of supply estimates how long it would take to sell through all current inventory at the existing sales pace, assuming no new listings came onto the market. Lower figures generally favor sellers, since limited inventory relative to demand supports pricing and shortens time on market. Higher figures tend to favor buyers. Anything under roughly six months is traditionally considered a seller’s market, which is where 5.09 still sits.
What This Means for Buyers and Sellers
For sellers, September brought a welcome pause. Prices stopped falling and the sold-to-list ratio held at 98.15%, meaning accurate pricing still earns near-asking offers. But 1,338 new listings arrived in a single month, so your competition grew. Plan for 36 days or more on market and price against what is actually selling, not against the $600K that new listings are asking.
For buyers, conditions remain favorable without getting better. Inventory is high by recent standards at 3,597 active listings, and homes are sitting long enough to inspect and negotiate properly. The signal to watch is pending prices running above closed prices — if that persists, the discount window may be narrowing.
As always, conditions vary significantly by neighborhood and price point. A condo in Cherry Creek and a single-family home in Green Valley Ranch are effectively different markets, so working with an agent who knows the specific submarket remains valuable.
Data source: Realtors Property Resource (RPR), September 2026, based on Denver, CO listings for single-family, condo, townhome, and apartment properties.
To see how the market moved over the quarter, compare these figures with our Denver housing market update for August 2026. Check back each month as new figures are released.